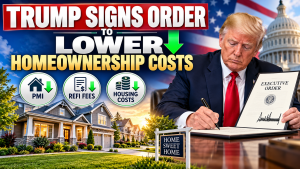
President Trump signed a new executive order on October 22, 2026, aimed at reducing the cost of homeownership, and there are a couple of provisions that could make a real difference for homeowners, including here in St. Louis. The order focuses on eliminating unnecessary mortgage insurance, reducing refinancing costs, and making it easier and less expensive to build homes.
One of the more interesting provisions would require Fannie Mae and Freddie Mac, subject to approval by the Federal Housing Finance Agency (FHFA), to establish a pilot program to automatically identify homeowners who have built up enough equity to cancel their private mortgage insurance (PMI). Currently, many homeowners continue paying PMI even after their home has appreciated enough to potentially qualify for cancellation, simply because they don’t know they qualify or don’t want to go through the process and expense of getting an appraisal.
Under the proposed pilot program, automated valuation models could be used to determine whether homeowners meet the equity requirements and eliminate PMI without requiring them to initiate the process. There is an important catch, however. The pilot would apply only to mortgages originated after the program is established, so homeowners with existing loans would not automatically benefit from this provision.
Another significant part of the order involves title insurance on refinances. The President is directing FHFA, subject to certain conditions, to expand an existing pilot program that allows Fannie Mae and Freddie Mac to accept automated title reviews instead of traditional lender’s title insurance on eligible refinance transactions. The order also calls for considering the elimination of certain appraisal requirements, income verification, and other fees on qualifying refinances.
As someone who has been involved in real estate for more than 40 years, I certainly understand the importance of protecting property ownership and ensuring clear title. However, I also believe there are opportunities to reduce unnecessary costs, particularly when someone is simply refinancing a property they already own. The key will be making sure that reducing costs doesn’t come at the expense of adequate protection against title defects and other risks.
The order also establishes a task force to streamline approvals and encourage more manufactured and factory-built housing, with recommendations due within 180 days. Additionally, it directs the Departments of Agriculture and Veterans Affairs to reduce interest rates on certain direct home loan programs, subject to applicable laws and available funding.
I’ve said before that making housing more affordable requires more than simply trying to push home prices down. Reducing the cost of financing, eliminating unnecessary fees, and making it less expensive to produce new housing are all important pieces of the puzzle. These are areas where even relatively small savings can make a meaningful difference to buyers and homeowners.
Of course, signing an executive order doesn’t mean these changes take effect immediately. Much of this will depend on FHFA and the other agencies developing and implementing the programs. It will be interesting to see how quickly that happens and, more importantly, how much of the savings actually make it into consumers’ pockets.
You can read the complete executive order here.